Renewed buying in U.S. technology shares is putting business performance and valuations back in focus. Recent earnings provide a window into how major internet companies are navigating technological change.
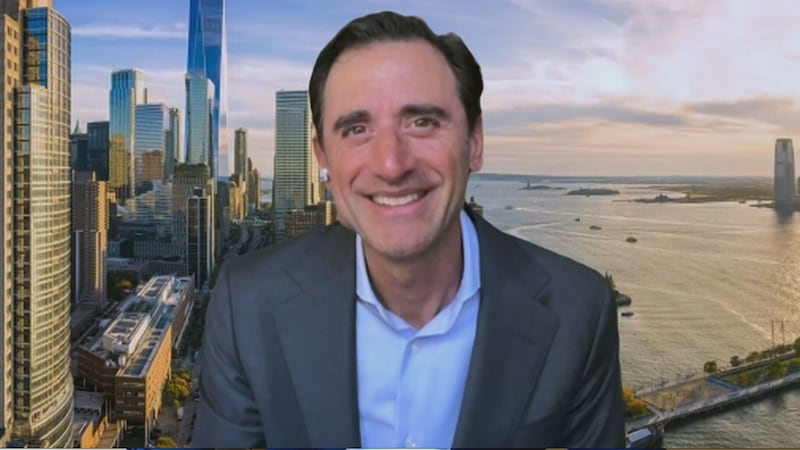
BNN Bloomberg spoke with Ron Josey, U.S. internet analyst at Citi, about his views on the sector and the investment cases for Airbnb, Alphabet and Amazon.
Key Takeaways
- Stronger U.S. online advertising and e-commerce activity, alongside AI investment, support Josey’s confidence in continued technology sector growth.
- AI travel agents could expand beyond accommodation bookings to arrange transportation, groceries and activities, with Josey expecting Airbnb’s plans to become more tangible in 2027.
- Google’s transition to AI-powered search is creating monetization challenges, with Josey looking for revenue growth to catch up with increased search activity.
- Access to computing capacity is a major competitive factor in cloud services, with Josey highlighting Google’s chips, distribution, data centres and AI models.
- Amazon is Josey’s top choice, supported by its retail performance, improving profitability and expectations for AWS revenue growth above 40 per cent in both 2027 and 2028.
Read the full transcript below:
LINDSAY: Welcome back. It’s time now for Hot Picks, and our next guest covers the tech sector. So let’s bring in Ron Josey, U.S. internet analyst at Citi. It’s great to have you join us. Good morning.
RON: Thanks for having me.
LINDSAY: Of course. Before we get to your Hot Picks, I want to just get your sense and hear what you think about what we’re seeing with the markets today, because it’s quite a reversal. After seeing a tech sell-off, we’re now seeing some renewed interest, some renewed hope when it comes to the technology sector. Do you think that’s justified?
RON: I do. I mean, look, we just came out of third-quarter earnings not too long ago. What we heard from so many different companies is not just the macro doing better. We hear that coming through from better advertising, greater e-commerce sales. We’re seeing that specifically here in the U.S., and frankly, I think that’s falling down or following or flowing down to the companies themselves. And so not only is e-commerce doing better, online advertising better, but of course, you also have the AI investments that are being made. And with the results that we saw at Google Cloud, with the results we saw at AWS, and accelerating revenue, or at least potentially here at Meta, you know, I think we’re seeing a lot of, call it, potential for continued growth across the macro that gets us pretty excited. And so that’s why I’m not surprised to see a reversal here, and hopefully some continued momentum going forward.
LINDSAY: Okay, and you mentioned that AI investment, and speaking of that, your first hot pick today has just announced that it’s building its own AI travel agent, so that’s Airbnb. Tell us what opportunities you see here for Airbnb.
RON: Yeah, look, I mean, there’s no doubt that travel is one of the first things that generative AI or AI-type tools are changing how you and I research and look for travel. Airbnb has something that I think is differentiated relative to others out there. They have differentiated inventory that is specific to them. You have a dedicated base that goes to them directly via app direct. I think over two-thirds of their users go directly their app and directly to their site. I think 90 per cent goes to their site.
And then now, as we enter a — this AI world where AI agents can actually do the transaction themselves, we’re looking for Airbnb to revamp their search process. And in so doing, they talk about launching an agent that can help users book not just the stay, but pretty much everything around the stay, which probably means getting to the stay, getting to the home, driving to the home, ordering groceries, maybe renting your skis and things along those lines.
All this is happening as AI is a bigger part of Airbnb’s business. They call themselves an AI-native company, and so now that we’re seeing this on the come, and all this sort of becomes more real, I would say in 2027, there — there’s some hope here. There’s a lot of potential for room nights to continue to grow, and that’s what gets us excited. They’re rebuilding their company or reinventing their company around AI.
LINDSAY: Yeah, it is really interesting to see how that’s going to pan out. I’m not sure whether they have a time frame on that, but it should be interesting to see. Your next pick is Alphabet. This company’s had — had a bit of a rough go lately, but the stock seems to be turning around, and that’s because Google’s new AI system has apparently found this way to double compute in the same space, and it looks like investors are liking this idea by Google. But tell us more about why you like Alphabet right now.
RON: Yeah, there’s a lot going on at Google, and frankly, we like Alphabet. We also like Amazon. That’s actually our top pick. We like Meta as well. But on Google specifically, their cloud business is operating extremely well. You saw growth reaccelerate. A lot of that is from the core Google Cloud platform that they continue to sell, which is, you know, their SaaS-based business. But then you also have their ability or their recent ability to sell their TPUs externally, and so that’s something that’s driving greater growth. We think can drive increased profitability as well.
The big debate on Alphabet and Google overall, though, is what’s going to happen in search, and the fact that their search business decelerated — a 12 per cent growth — on their own disruption of going from 10 blue links into AI Overviews and AI Mode. That’s something we think that we will work through over the next year or so. But that’s causing a little bit of pause. And to your comments — or the rough go on shares — but at the end of the day, you know, look, Google has multiple properties with over two billion monthly active users. I think 15-plus properties at over 500 million monthly active users. They’re going to figure out search and monetization.
We think that probably comes sooner, but that’s the debate that’s going on right now, is: Can the core search business sort of stabilize their growth rates here, maybe even reaccelerate, as query growth actually, you know, grew at [unclear] a five-year high, which tells you that people are doing more on Google now? We need monetization to catch up.
LINDSAY: Yeah, it’s a pricey stock, though. Like, I wonder if Google stock price is too high for new investors to buy in at this rate. Is there the risk that maybe CoreWeave could offer similar exposure to the AI trade, just as an example of a company, and create greater competition?
RON: Well, the benefit of Google is their vertical integration, and, you know, we talked about — when I say vertical integration, I mean they own the TPU, so they own the chips. They clearly have the distribution with GCP and the data, but then also they’re building out their own data centres, and they have their model with their latest models, Argon, Carbon, as an example, around their Gemini family.
The challenge that I think Google has and others is they need to have the capacity, and so the more capacity that they can bring online, either through themselves or through partners, should be monetized pretty immediately. And that’s a huge opportunity in our view in terms of what can come down the pike and what can drive continued Google Cloud growth going forward.
As it relates to CoreWeave, my colleague Tyler covers them. He’ll have more to — more to share there. But I will tell you, Google is — and Amazon and Meta and many others — there’s a major fight for capacity out there, and I think Google is one that is absolutely focused on building that up.
LINDSAY: Well, let’s get to your last hot pick then, because it is Amazon. I know you touched on them a couple times, but tell us more about why you also like Amazon.
RON: Yeah, look, I mean, we think their core retail business is executing extremely well. You know, they’re growing in the high single digits. At least we think they will continue to grow there from a retail perspective in the States. And their AWS business, they are quickly becoming a winner in a — in AI overall, and their AWS business and revenues are showing that with accelerating growth.
I think a big unlock this last quarter on Amazon were several things, but I’ll just highlight one in particular: the fact that — that their AWS growth rate is expected to be over 40 per cent for the next two years. So for 2027 and 2028. That tells you the visibility that they’re seeing in the business.
On top of that, we just talked about Google driving or looking for greater capacity so that they can monetize that pretty quickly. We actually think Amazon is amongst the best positioned from a capacity perspective, which makes them, you know, our top pick overall.
And so we like what we’re seeing in AWS. We think the North America retail business continues to gain share. Agentic commerce is an opportunity overall. We don’t think that’s the threat. We think they actually have a good strategy there, and that will be more apparent as time goes on. And profitability is improving. All those three things together, we think, make Amazon quite attractive from an equity perspective.
LINDSAY: Okay, we got to leave it there. Ron Josey, U.S. internet analyst at Citi. Great to have you join us. Thank you.
RON: Thanks for having me.
| DISCLOSURE | PERSONAL | FAMILY | PORTFOLIO/FUND |
|---|---|---|---|
| ABNB:NASDAQ | N | N | Y |
| GOOGL:NASDAQ | N | N | Y |
| AMZN:NASDAQ | N | N | Y |
---
This BNN Bloomberg summary and transcript of the Nov. 11, 2026 interview with Ron Josey are published with the assistance of AI. Original research, interview questions and added context was created by BNN Bloomberg journalists. An editor also reviewed this material before it was published to ensure its accuracy and adherence with BNN Bloomberg editorial policies and standards.