Canadian real estate stocks have had a rocky few years. The discussion looks at where individual businesses could find growth in 2027.
BNN Bloomberg spoke with Lorne Kalmar, a real estate analyst at Desjardins, about Primaris REIT, Extendicare and Sienna Senior Living.
Key Takeaways
- Kalmar says interest rates will largely drive Canadian real estate stocks in 2027, and Desjardins expects only a modest decline in long-term bond yields.
- Kalmar says Primaris has built a portfolio of mostly Class A malls and is seeing demand for space from discretionary retailers after years of virtually no new retail supply in Canada.
- Kalmar sees home care as a lower-cost way to meet the needs of Canada’s aging population as hospitals and long-term care homes face capacity constraints.
- Sienna expects high single-digit growth in its long-term care business in 2026, compared with historical growth of 1 to 3 per cent, and Kalmar sees room for growth from replacing older homes.
- Kalmar estimates Sienna has about $500 million in acquisition capacity and thinks a portfolio purchase could give it an immediate foothold in Quebec.
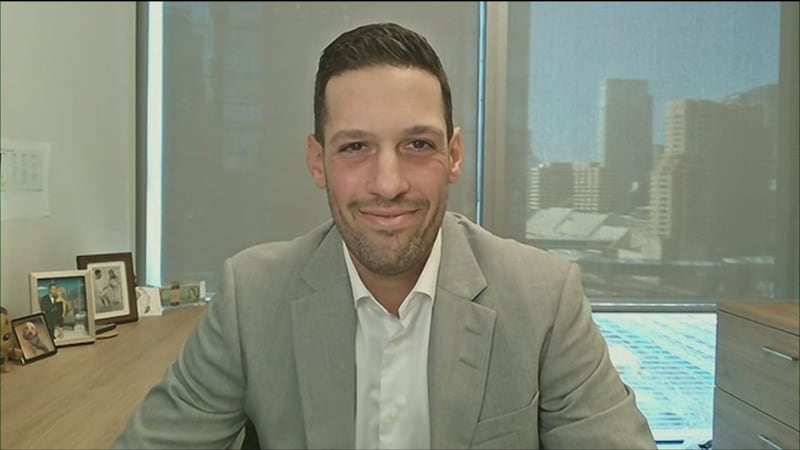
Read the full transcript below:
LINDSAY: It’s time now for Hot Picks, and our next guest sees opportunity for three REITs achieving growth through its own key acquisition strategies. Let’s get more now from Lorne Kalmar, real estate analyst at Desjardins. It’s great to have you join us. Good morning.
LORNE: Good morning. Thank you for having me.
LINDSAY: Of course. Before we get into your three names, let’s just talk about the Canadian real estate market as a whole. Do you think that it’s finally found a bottom? Are you starting to see a recovery? What’s the state of it in your eyes right now?
LORNE: It’s been a rocky road here the past sort of four-plus years as interest rates have really wreaked havoc on, on the sector. It continues to appear to be as though performance will largely be interest rate-driven in this environment, so whether you see a meaningful amount of upside or not, I think, is contingent on how your outlook for — or what your outlook for interest rates are. Here, ours is for — on the Desjardins side — is for a modest downtick in the long-term bond yield, so nothing major. So I don’t know that’s enough necessarily to lead to massive levels of outperformance. But as always, while top-down might not be the best approach, we do think there are some great bottom-up ideas if you’re willing to put in the work.
LINDSAY: Okay, so let’s talk about some of those ideas. Your first pick is Primaris Real Estate Trust. Tell us why you like this one.
LORNE: Yeah, this is one we’ve liked for a long time. They are owners and operators of malls. They — you know, malls had for a period of time really fallen out of favour. And what we’ve witnessed as we’ve emerged from COVID is that its performance is very much bifurcated. So the higher-quality assets are performing very well, while the lower-quality assets are falling by the wayside. And the strategy that Primaris has undertaken is to acquire higher-quality Class A malls, largely in, in secondary or, I would say, non-VECTOM markets for the most part. Although recently they have also dabbled in the VECTOM markets as well, and as a result, they built a portfolio over the past, you know, three, four years that’s predominantly now these Class A-type malls that are performing quite well.
LINDSAY: Why do you think retail real estate, like, it seems like it’s proved to be more resilient than expected?
LORNE: Yeah, I mean, within the REIT space, the majority of the retail REITs are grocery-anchored, necessity-based retail landlords, and those are the type of retailers that do well regardless of economic cycle. But what we’ve seen with Primaris is that even the discretionary-type retailers are clamouring for space, and a part of that has been a strategy shift towards more discount, which we’ve seen, like, with the grocers, with the rapid growth of the TJX banners and Dollarama. But also, you know, there’s been voids left that, you know, for example, HBC, Toys “R” Us. You know, people still need toys, but the stores themselves, whether it be, you know, typically it was balance sheet reasons, they didn’t work. So there is opportunity there for discretionary-type retailers to fill that void.
And at the end of the day, as is so often the case, the supply side is a very important consideration as well, and there has been virtually no new supply added in Canada on the retail front for many years. So what you have is a lot of retailers that are still playing catch-up from the, I guess you’d call it a moratorium on physical growth that started when e-commerce came on the scene. And a lot of them pivoted their focus towards building out their e-commerce networks, and as a result, the physical store growth kind of fell by the wayside. Now they’re in catch-up mode, coming out of COVID, realizing that, you know what, this omnichannel approach, where you have both the e-commerce and the physical, is really the best path forward in today’s world.
LINDSAY: Okay. Next up is Extendicare, and we know Canada’s aging population has created some demand for home care. Why do you see Extendicare as the best way for investors to kind of benefit from that trend right now?
LORNE: There — there’s really three seniors names in our coverage, and Extendicare is really unique in that they are more services-focused, and the largest part of their business is home care services. So people, you know, PSWs, nurses come into your home, and the reality of the situation that we’re in in this country is that we have a rapidly aging demographic, as you alluded to, and not many ways to really deal with it. Right? The hospital system is stressed. Long-term care system is stressed. They’ve — you know, there’s been a big push to add homes, but it appears as things stand right now, there’s still going to be a large shortage. So the next option is home care, which is the most efficient by far in terms of cost-wise. And as the largest home care provider in Canada, we see Extendicare as being very well positioned to benefit from this.
LINDSAY: You also like Sienna Senior Living, though, in this kind of same category. Tell us about that one.
LORNE: Yeah, as I — as I mentioned before, right? The whole seniors demographic wave is underpinning a lot of the strong performance in the REIT sector that we’ve seen from the names that we’ve seen. So Sienna has a diversified portfolio, about 50-50 long-term care, retirement. And while we certainly understand the merits of going pure-play retirement in this environment, we think that the long-term care story has been underappreciated. Something that’s historically been a 1 to 3 per cent growth business. Sienna is forecasting high single-digit growth for this year, and we also see upside via the long-term care redevelopment program, which is the redevelopment of older, called Class C homes, into newer Class A homes.
LINDSAY: What about acquisitions? Like, does Sienna have some of that down their pipeline? Why is it important for the next phase of the growth story for a company like Sienna?
LORNE: Absolutely. So they have been extremely active on the acquisition front. They are fortunate in that because they’re a diversified portfolio, they have quite a much broader opportunity set. They can buy both retirement and long-term care. They expect to remain very active. They’ve got the cost of capital to remain very active, and, you know, one of the things that they’ve mentioned is they expect to enter the Quebec market. We believe this would likely be a — via portfolio transaction, right? Give them immediate scale. So we expect that they’re going to continue to be busy on that front going forward.
LINDSAY: Is that — do you think — something that a lot of these companies should be focusing on moving forward? Is more M&A activity?
LORNE: To the extent that your cost of capital allows it, we would never sit here and suggest growth for growth’s sake. If you can find assets that are accretive on an earnings basis, accretive on a quality basis, and you have the balance sheet to do it, then we are all for it. I would say in Sienna’s case, they’re actually running their leverage at about 5.7 or five — 5.8 times net debt to EBITDA, which is well below the 7.5 to eight times target range they have, and we estimate that gives them about $500 million [in] acquisition capacity on their balance sheet alone. So a lot of room for them, a lot of runway for them.
LINDSAY: Okay, and then as we head into 2027, I know we kind of talked about this off the top, but do you really see 2027 as a, as a recovery year for the Canadian real estate sector, or is it still going to be a bit stagnant until heading into 2028? Is it like a slower growth period that we can expect to see?
LORNE: Yeah, Lindsay, I would love to tell you, yes, we’re super rah-rah on REITs going into 2027, and I think there is a blue-sky scenario here, as there always is. Right, you get a little bit of cooperation on rates, maybe you see some reprieve on — in the Middle East and on the inflation front and on the trade war side of things. So perhaps if that all comes together, then, then maybe there’s some room for some outperformance. But if we kind of stay steady state here over the next 12 months, it’s tough to get really excited about the sector. Unfortunately.
LINDSAY: Okay. Well, appreciate your honesty there. We’ll have to keep an eye on the sector and see how it fares. Lorne Kalmar, real estate analyst at Desjardins. Great to have you join us. Thank you.
| DISCLOSURE | PERSONAL | FAMILY | PORTFOLIO/FUND |
|---|---|---|---|
| PMZ.UN:TSX | N | N | Y |
| EXE:TSX | N | N | Y |
| SIA:TSX | N | N | Y |
---
This BNN Bloomberg summary and transcript of the Nov. 18, 2026 interview with Lorne Kalmar are published with the assistance of AI. Original research, interview questions and added context was created by BNN Bloomberg journalists. An editor also reviewed this material before it was published to ensure its accuracy and adherence with BNN Bloomberg editorial policies and standards.