Solid U.S. GDP data is reinforcing signs of economic momentum, with Brent Joyce also seeing evidence of improvement globally. He says artificial intelligence is contributing to that strength, but it is not the only driver.
BNN Bloomberg spoke with Brent Joyce, chief investment strategist at BMO Private Wealth, about how the economic backdrop is shaping his assessment of stocks, bonds and monetary policy.
Key Takeaways
- Higher bond yields are improving the income and diversification benefits of fixed-income investments, Joyce says.
- Joyce views current yields as more normal levels that reflect economic growth and inflation after years of exceptionally low rates.
- Utilities and real estate warrant caution because yields may not fall enough to support these interest rate-sensitive sectors over the medium term.
- Higher borrowing costs impose discipline on governments and businesses by making financing decisions more demanding.
- Joyce argues that central banks can demonstrate their commitment to controlling inflation without delivering all the rate increases priced into the bond market.
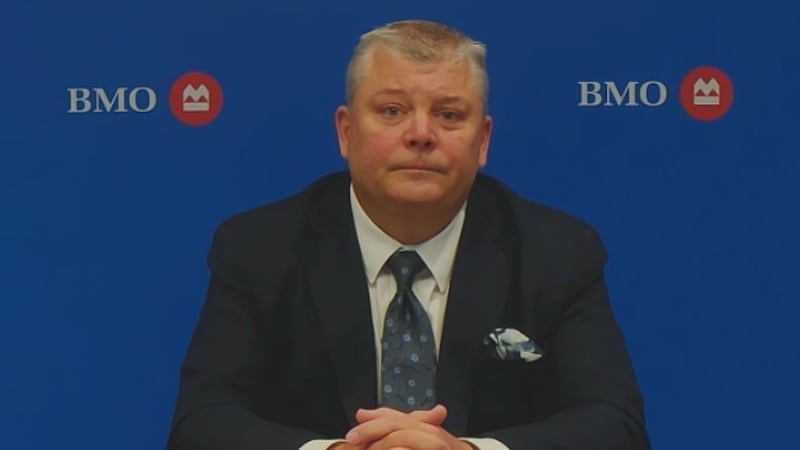
Read the full transcript below:
LINDSAY: U.S. futures are trading higher this morning, driven by technology stocks. These gains come amid swings in the bond market, with the yield on 10-year Treasuries briefly reaching their highest point since 2002 before pulling back. Joining us now to share his perspective is Brent Joyce, chief investment strategist at BMO Private Wealth. It’s great to have you join us this morning. Good morning.
BRENT: Good morning, Lindsay.
LINDSAY: So we’ll start with that U.S. GDP data released yesterday, which kind of reinforced the idea, right, that the U.S. economy is still growing at a relatively healthy pace. What’s your biggest takeaway from the data, and what does that mean for the bond market?
BRENT: Yeah, it’s another piece of data that suggests the U.S. economy is on solid footing. I would say there’s been data coming in from around the globe that suggests the global economy is inflecting higher. Some of that obviously is the AI trade, but it’s not completely that. And you have to ask the question, I think, is what the bond market is sort of raising an eyebrow and saying: When is too much of — when is a good thing too much of a good thing?
LINDSAY: Over the last month, almost every sector, though, has struggled except technology and communication services. We’re seeing technology is really boosting the markets today once again. Does this create a buying opportunity in beaten-down sectors?
BRENT: Yeah, for the well-diversified investor, whether that is looking at Canadians who have U.S. equity exposure and Canadian equity exposure — they’re very complementary. We have had a trade this year that has been communication services, technology, financials here in Canada, and energy. And then when those things aren’t working, we’ve seen things flip over to health care, materials, financials in the U.S. And so there’s been stuff working to keep markets afloat, but under the surface, you’ve seen, like you mentioned, a couple of sectors have held us up over the past three months, and then seven, eight sectors on both sides of the border have been weak.
I think you need to be careful to be selective in some of those beaten-down sectors. You want to look for things that have some longer-term health. Areas that are going to be pinched by higher bond yields — utilities, real estate, things of that nature — I think you want to be a little bit more discerning about those. We think yields have gotten to a point where we’re getting to levels here that are getting quite attractive for fixed-income investors, and probably at the point where they’re going to start to bleed, and people are going to think about what’s some damage that might be done. So yields could come off a little bit in the near term, but those very interest rate-sensitive sectors, we don’t think yields come down enough to help those out for the medium term.
LINDSAY: In the meantime, though, bond yields are kind of offering investors meaningful income once again, right? Like, how are you thinking about the trade-off between owning stocks and owning bonds right now?
BRENT: Yeah, I like bonds more today than I did a month ago, three months ago, and a year ago. First, we need to put in context a lot of headlines around bond yields have hit 20-year highs, 25-year highs. U.K. first market getting a six per cent yield, and the U.K. being a bit of a special case. But in general, mid- to longer-term bond yields should reflect where nominal economic growth is. Nominal meaning real GDP growth plus inflation.
And so, if you put two and a half and two and a half, or two and three, or three and two, you’re — any combination of that — bond yields that are in the high threes to mid fives across Canada, U.S. and elsewhere, those are normal. Those are reflecting the strength of the underlying economy and somewhat elevated inflation. They are paying investors, bond investors, more handsomely than today. But for us, as using them as a diversification tool, they’re now primed to be able to provide that if we were to see some weakness.
LINDSAY: Okay. So this is more of a — of a normal environment after years of exceptionally low rates, then? Is that what you’re saying?
BRENT: Absolutely. If you look at the past 25 years, we had a dot-com bust. We had great financial crisis. We had COVID. We had quantitative easing. All kinds of intervention by monetary policy and by treasuries to keep bond yields low, and now we’ve exited those. We’ve got no more QE from most central banks, and it’s really now a free-floating bond market that is setting the price.
Remember, bond yields are the price of money, and we’ve got lots of corporations that are seeking money to invest in good projects. We’ve got governments clearly that continue to borrow, and so when you have excess demand for anything, you should see the price go up. Yields being the price of money, we have bond yields now that better reflect where we are in the global economy.
The good news there is it imposes discipline. Discipline first and foremost, I would say, on governments, and then certainly on businesses to be more discerning about the next data centre or the next M&A activity, given where the price of money sits today.
LINDSAY: Okay. When it comes to central banks, you’ve described recent central bank moves as credibility hikes. What do you mean by that?
BRENT: Well, we had certainly the Fed’s credibility being challenged with Jerome Powell and Kevin Warsh now trying to make a statement. There was a view that he was coming in as Trump’s sort of handpick, and in the face of what central banks are supposed to do, follow their mandate in the U.S. It is a dual mandate, as we know: inflation and full employment or growth.
At the moment, there are no concerns on the employment front or on the growth front. The concern might be that it’s running too good, and certainly the cost of living and inflation remains the job that needs to be done. And so, central banks cannot ignore that inflation side of their mandate.
My argument today is these credibility hikes don’t need to be where the bond market is pricing at four and five rate hikes in the span of six or eight months. That — that is probably too much in order to get the job done. You look at inflation expectations in the five-year and in the 10-year space, and they remain quite stable. And so the Fed, being hawkish, and the bond market doing some of its job for it, is getting the job done on keeping inflation expectations anchored.
Not anchored at the right number, perhaps. It’s about 2.3, 2.4 in the U.S. And I think, given all the good things that are happening in the economy, that might be an inflation level that probably is welcome to people today, but is one that we’re going to have to live with longer term.
LINDSAY: Okay, we got to leave it there. Brent Joyce, chief investment strategist at BMO Private Wealth. It’s always great to have you join us. Thanks so much.
---
This BNN Bloomberg summary and transcript of the Oct. 1, 2026 interview with Brent Joyce are published with the assistance of AI. Original research, interview questions and added context was created by BNN Bloomberg journalists. An editor also reviewed this material before it was published to ensure its accuracy and adherence with BNN Bloomberg editorial policies and standards.