The U.S. midterm election results have added a political dimension to the debate over artificial intelligence spending. Attention is turning to how the technology sector will navigate the changing landscape.
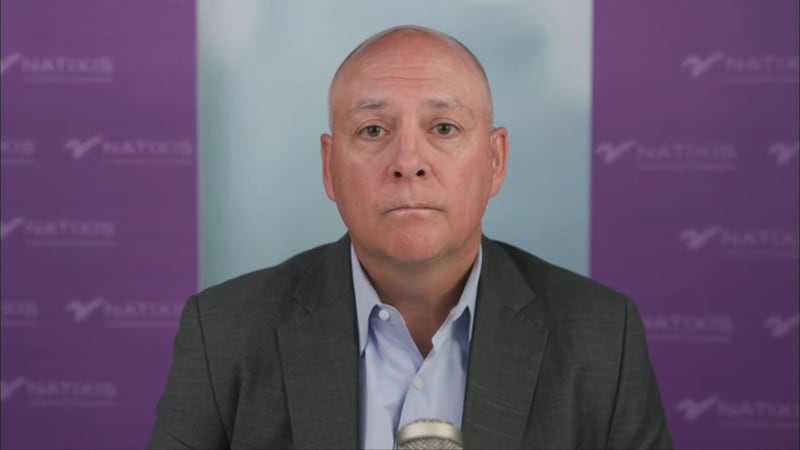
BNN Bloomberg spoke with Jack Janasiewicz, portfolio manager and lead portfolio strategist at Natixis Investment Managers Solutions, about the implications for AI investment and the questions facing Nvidia.
Key Takeaways
- Political opposition could delay AI data centre construction and increase costs, but Janasiewicz says the underlying investment opportunity remains intact.
- A slower construction cycle could benefit large cloud providers as computing capacity becomes scarcer and existing facilities become more valuable.
- Extensive order backlogs could support demand for Nvidia’s graphics processing units over roughly the next year and a half, with construction delays posing risks farther out.
- Electricity supply and grid capacity remain constraints, potentially encouraging greater use of existing infrastructure and easing spending pressures.
- Nvidia’s approach to infrastructure financing and the possibility of tighter U.S. chip export restrictions on China are key uncertainties to watch.
Read the full transcript below:
LINDSAY: With recent challenges for Nvidia, there’s another issue for the AI trade: the U.S. midterm elections. Our next guest thinks the next big challenge for tech is gaining political approval after Democrats swept the House and the Senate. Let’s get more now from Jack Janasiewicz, portfolio manager and lead portfolio strategist at Natixis Investment Managers Solutions. Good morning. Great to have you join us.
JACK: Yeah, thanks for having me back.
LINDSAY: So let’s start there. Like, you see politics as a real bottleneck for AI. Tell us more about that and how you feel the sector needs to kind of navigate that, that area.
JACK: Sure. And this is just another headwind that sort of enters into the equation. And I think a lot of people are looking at Texas as the template going forward. But, you know, remember, when you’re going through these political cycles, you know, job number one is to get elected, and you’re probably going to say a lot of things that are resonating with your constituents.
But once you get elected, that backdrop changes a little bit, and I think one of the things that needs to come into this equation is the thought process behind if you’re really going to put up a wall against the data centre buildout, you’re potentially forgoing, you know, the economic benefit, whether that be increased jobs and, more importantly, increased tax revenue, and obviously the growth backdrop there. And so that trade-off, I think, is going to have to come to the forefront.
But at the end of the day, our job here is to think about it in terms of delayed but not destroyed. And I think that’s what we have to think about going forward here. Politics certainly entering the, the equation, maybe the cost of the data centres increases on the back of that, but delayed versus destroyed. I think that’s the key takeaway from us.
LINDSAY: There are some companies, though, that do stand to benefit from this bottleneck. Is that right?
JACK: Sure, and I think, you know, this probably slows down the capex cycle a bit, and as that capex — as the capex cycle slows at the margin, you know, that’s going to create a little bit of a supply and demand imbalance, and this is probably a chance where you get a little bit of that demand cooling, and supply has a chance to catch up, maybe giving us a mini inventory cycle going forward.
But I think the key here is, you know, scarcity and what’s going to be scarce, at least in the interim, probably going to be some of that compute and that compute space. Who’s the one to stand to benefit from that? It’s probably going to be the hyperscalers. So we certainly would expect, at least in the short term, the hyperscalers to really benefit from the potential slowing here as a result of this political backdrop.
LINDSAY: It does sound like AI is still worth the investment, though, in your view. Is that right? Given everything, the political backdrop, all the volatility we’re seeing right now with certain big companies, it’s still an opportunity.
JACK: Yeah, and I think that’s the case here. I think the AI trade is still alive and well. You know, there’s certainly plenty of demand that we can point to with regard to compute, which is certainly projected to last for probably out to maybe 2020 — 2030, I should say. So that cycle continues to work its way through.
The question still is going to be that ROI’s backdrop. I think over the last comments that we’ve heard from some of these providers over the last couple of days gives a little bit more credibility to that. Yeah, we are seeing this continuing to work its way through the system. There’s still demand there, and there’s still some runway where you could continue to see that ROI benefit slowly creeping up sooner than later. And I think that’s giving some confidence to the market here with regard to the AI trade.
LINDSAY: I wonder, though, because obviously we’re talking about politics and how that kind of, you know, deals with the AI buildout. Obviously, there’s a lot of talk now after the Democratic sweep of a potential data centre moratorium in the U.S. When it comes to building more of these data centres across the country, if those projects are delayed, what does that mean in the near term for demand for Nvidia’s GPUs, for example?
JACK: You know, I still think you’re looking at a backlog order that’s quite extensive, and so when you start to talk about these potential delays, that’s something that I think impacts that demand structure farther down the curve. So I think over the next, let’s call it, year and a half or so, those orders will continue to be executed on, and so I think that keeps that demand in the short term supported going forward.
So, big difference in timing here, and hopefully, when we start talking about delays being overcome, by the time we’re looking out past those demand issues for 2027, 2028, these backdrops been settled, more clarity, and that cycle just starts back up again.
LINDSAY: Despite the scandal with Nvidia right now, I wonder: Does scarce power make its chips almost more valuable as customers look to — for more performance per watt?
JACK: Yeah, and I think this does brings a couple of things to the forefront. You know, certainly the grid, the capacity, the energy is still going to be a key bottlenecking issue going forward, whether it be from the political side or not. That’s one of the sticking points going forward here, so that remains to be an issue.
But I think it’s also going to put a little bit more pressure on the potential for the companies that have these positions in place to utilize what they have. And so, you know, we probably expect to see utilization rates pushing higher, which means more efficiency, maybe less spending at the margin. And I think that potentially could ease growth a bit, but that puts downward pressure on the inflation concerns and the growth backdrop. So, perversely, coming full circle, the rates backdrop could actually get a little bit of support from this sort of slowing of the cycle.
LINDSAY: I wonder, because I did want to stay on Nvidia for a moment, because obviously that’s the big story that we’re following this week, huge story, and it’s interesting. It’s coming at an interesting time when Nvidia is set to report earnings next week. What are you going to be watching for there?
JACK: You know, a lot of questions, I think, are — that are going to be hope — hopefully answered. You know, one, what does this mean going forward? You know, Jensen certainly had a big hand in terms of the big picture backdrop. Are we going to potentially see the cooling, if you will, of that circular financing?
You know, Jensen was certainly the visionary where he was going out and doing a lot of the capital investments to help build out the infrastructure sort of system. You know, does that start to slow a little bit? Are we going to continue to see or potentially see export controls being levied on Nvidia going forward?
So I think those are some of the bigger questions that we’ll look to answer, and I’m not sure they’re going to be able to answer some of that going forward. But certainly, those are some of the things top of mind that I’ll be paying attention to.
LINDSAY: Do you think we could see the U.S. government tighten restrictions on chip exports to China even further? And I know there’s a lot of speculation right now about what’s going to happen. But do you think that’s one thing that we could see?
JACK: That’s certainly, I think, a risk going forward here. And you’ve certainly seen, I think, a repricing of a lot of the AI-related names in the Chinese market. So, certainly something that’s a headline risk that could certainly play itself out.
LINDSAY: OK, we’ll leave it there. Jack Janasiewicz, portfolio manager and lead portfolio strategist at Natixis Investment Managers Solutions. Appreciate your time. Thank you.
---
This BNN Bloomberg summary and transcript of the Nov. 13, 2026 interview with Jack Janasiewicz are published with the assistance of AI. Original research, interview questions and added context was created by BNN Bloomberg journalists. An editor also reviewed this material before it was published to ensure its accuracy and adherence with BNN Bloomberg editorial policies and standards.