It’s artificial intelligence (AI) week. Not really, but Nvidia reports earnings (its first without former CEO Jensen Huang), and of course, Anthropic (ANT) is expected to go public.
The history of the A to H funding rounds features the likes of Sam Bankman-Fried in round B at a US$4.1 billion valuation in April 2022 to several strategic rounds by Google and Amazon and the who’s who of Menlo Park venture funds. The most recent round H on May 28, 2026, was at a valuation of $965 billion.
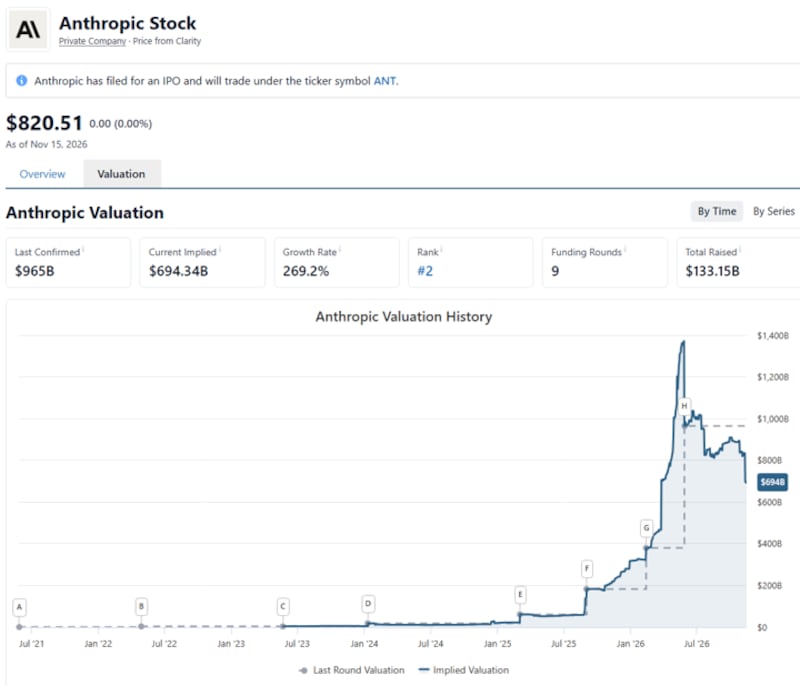
Many do not know, but accredited investors can participate in private markets with secondary exchanges like Clarity (formerly Hiive).
If Nvidia does not have great things to say in a post-Jensen world, sentiment could turn even harder and there is a small chance the ANT initial public offering (IPO) gets pushed back. While I do not expect this to happen, the risk is there.
With all the uncertainty, I love using naked put options to acquire shares. Volatility is high and the premium one receives is attractive. The big caveat is that with all naked put writing, you must be able and willing to own the stock at that price.
It’s not a risk-free income, it’s a way to earn while you wait, but you must want to own the stock.
With Nvidia, we did not like the risk return over the next 6-12 months above $214. That’s where it traded when Anthropic did its last raise. Looking to earnings this week and options expiry on Friday, when Nvidia gapped below $214 on Oct. 30, we sold a $180 put for one per cent to acquire a one per cent position.
We were not expecting the downside to play out the way it did. When it gapped down towards $180 on the huge tech sell-off on Nov. 5, we sold a $140 put for an additional one per cent return to add another oner per cent. If Nvidia is below $140 on Nov. 20, I’ll own two per cent at an average of $158.40.
If we trade down towards $140 today or before earnings tomorrow, I’ll sell another put at $120 building my position to three per cent and lowering my average cost. Today, Nvidia is six per cent of the index, and I am still building to half weight. Once there is some evidence of a bottom, I’d look to get to full weight.
For ANT, it’s likely to be similar to Broadcom in terms of market cap when it comes public this week if the $1.4 trillion cap estimate is reliable. So, it would be about 2.4 per cent of the S&P 500.
If the secondary market is any indication, and it’s often a decent guideline, I would not make ANT more than a one per cent weight at the IPO price (current secondary pricing is $820 billion valuation).
If the stock pops 25 per cent or more in the weeks following the start of trading, I’d cut it in half and look to accumulate on weakness using the high volatility in the options market (when they start trading) similar to my Nvidia exposure.
If the stock falls out of the shoot, I’d back up the truck at the $400 billion market cap round G valuation. I doubt it gets that low unless something much bigger is driving stocks lower.
I’m very bullish on AI, but some of the bubble(ish) valuations need time for earnings to grow into them and for some of the political guardrails to play out.
Follow Larry
YouTube: LarryBermanOfficial
LinkedIn: LarryBerman