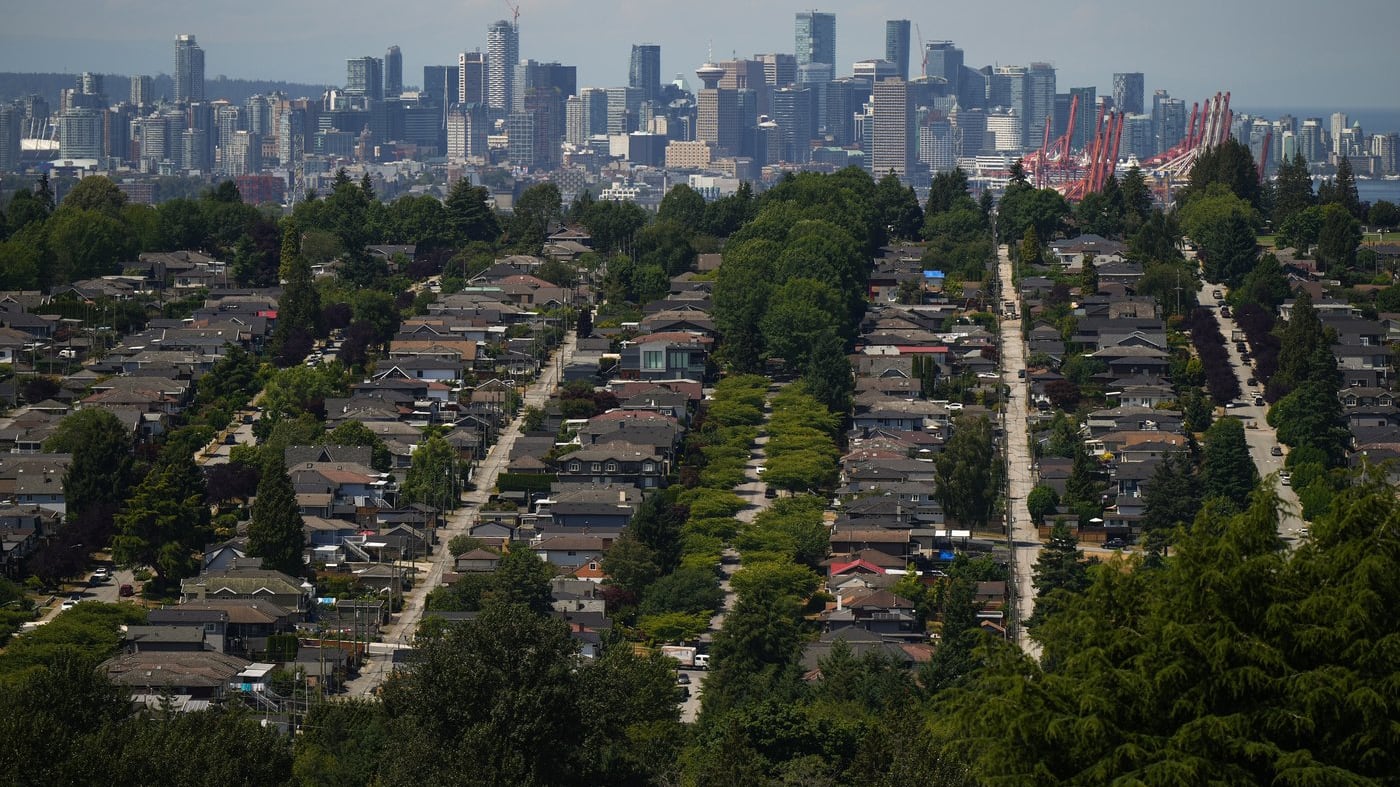
Homeowners may be tempted to take the mortgage rate offered in a renewal letter, but savvy borrowers see it as the start of a negotiation process that could lead to big savings.
With many borrowers now renewing at rates above what they previously locked in, mortgage professionals say the worst move is signing whatever arrives in the mail. The best results come from starting early, shopping around, and comparing more than the headline rate.
Kola Ifabumuyi, a certified mortgage planner with Mortgage Architects, suggests starting about four months out from your renewal date, or earlier for self-employed borrowers or anyone whose income has changed.
He advises homeowners to gather their mortgage statement and renewal offer, check how many years remain on the amortization, and decide what monthly payment they can afford. Anyone considering switching lenders should also start pulling together income documents.
Personal plans matter as well. For instance, when Ifabumuyi worked with a homeowner planning to sell soon after renewal, they focused on what the mortgage would cost until the sale and what it would cost to break the contract.
“(The client’s life) plans matter as much as the rate,” he said.
Steven Biderman, a certified mortgage broker with Mortgage Outlet, also warns about early renewal offers. Borrowers should understand when the new rate takes effect and whether accepting means giving up the benefit of their current rate before the term ends.
Renewing with your existing lender is usually the simplest route, especially if your finances have changed and you want to avoid a new application, Biderman said.
Ifabumuyi agreed that staying is easier and a basic renewal often avoids a new approval process, which can be beneficial if your income has fallen. But the convenience may come at the cost of a higher rate.
Switching requires approval from the new lender and may involve appraisal, legal, registration and discharge fees, so borrowers should ask if any of those costs are covered. Switching at the end of a term generally avoids an early-break penalty. Biderman noted that mortgages secured by collateral can also come with additional costs beyond those typically associated with a conventional mortgage.
Some borrowers also miss an opportunity to qualify at a lower rate. If an eligible uninsured individual switches between federally regulated lenders, they avoid the usual stress test if the borrower doesn’t increase the loan or extend the amortization period.
Ifabumuyi offered an example. On a $500,000 mortgage with 20 years left, the monthly payment at 4.5 per cent is $3,152.03, compared with $3,702.50 at a 6.5 per cent stress-test rate. Qualifying at the lower rate reduces the monthly approval hurdle by $550.47.
If you find a better offer, it’s also worth asking your current lender to match it.
Ifabumuyi suggests bringing a written offer with comparable terms and saying something like: “I’d prefer to stay. Your five-year fixed rate is 4.79 per cent, and I have a comparable offer at 4.5 per cent. Can you match it and send your best offer in writing by [date]?”
Small differences can add up. On $500,000 with 20 years left, a five-year fixed rate of 4.5 per cent instead of 4.79 per cent saves $4,629 in payments over five years, Ifabumuyi calculated.
If the first answer is no, ask the bank’s mortgage retention team to review it, and leave enough time to switch to a new lender if needed.
Biderman said a conversation alone can sometimes prompt a better offer, even without a formal competing quote.
“There is no guarantee of a match, but it costs little to ask,” he said.
If the bank improves its offer, compare the full terms, not just the rate.
Biderman suggests looking at the term, fixed versus variable structure, prepayment privileges, portability, payment flexibility and any restrictions that could matter if plans change. A mortgage broker can compare options from multiple lenders.
While renewing sets a new rate and term on your existing mortgage, a refinancing changes the loan itself — often to borrow more or extend the amortization — and usually requires new approval.
Refinancing can make sense if the homeowner needs extra cash for big-ticket spending like home repairs, buying out a co-owner, or paying off high-interest debt with a clear repayment plan, Ifabumuyi said.
He cautioned against refinancing just to lower payments. At 4.79 per cent, extending a $500,000 mortgage from 20 to 30 years cuts monthly payments to $2,606.09 from $3,229.18. But after five years, the borrower owes $42,096.60 more and has paid $4,711.64 in additional interest, before fees.
Biderman said the key is to examine the reason for refinancing, the costs, the new payment, and the long-term consequences before deciding.
“A good mortgage decision isn’t necessarily the one with the lowest rate,” he said. “It’s the one that makes the most sense for you.”
This report by The Canadian Press was first published Oct. 19, 2026.
Kumutha Ramanathan, The Canadian Press