All things considered, Julia Chung had a lot working in her favour when she was tasked with settling the estates of not one, but two, uncles who died earlier this year.
As a financial planner, she has more money know-how than most. And her uncles had each clearly communicated their end-of-life wishes and ensured vital information was accessible.
Even still, it’s been exhausting.
“When you’re experiencing grief at the same time, which I definitely have been, there were moments where I was like, ‘I literally can’t think,’” Chung, CEO of Spring Planning, said in an interview from Vancouver.
People often name someone they love and trust to be executor of their estates, which involves settling debts, managing assets and tying up myriad other loose ends. It’s a time-consuming, emotionally heavy and logistically dizzying role that can sometimes bring a financial hit. Those agreeing to take on this duty should have a clear-eyed understanding of what it entails and an openness to sharing some of the load, experts say.
“This is hundreds of hours of work,” said Erin Bury, co-founder of estate planning firm Willful. “This is not a minor task, and it involves a lot of co-ordination and expertise that you may not possess.”
Expect the whole process to take at least a year — maybe much longer.
Responsibilities in the immediate aftermath include making arrangements for the body, and any funeral or celebration of life. Executors need to get copies of the death certificate and track down the original will. They also need to secure the deceased’s property — changing locks and making sure insurance doesn’t lapse.
Later, there’s communicating with beneficiaries, getting in touch with banks and service providers and filing final tax returns.
Executors should be prepared to go through probate, a legal process where a court deems the will valid and gives the executor the authority to carry it out, though it doesn’t apply in all cases.
Until probate is complete and funds from the estate can be unlocked, an executor may have to front the cost of the funeral, lawyers, accountants and bills that still need to be paid.
Executors are entitled to compensation for their time. If the amount isn’t set out in the will, there are limits under provincial legislation.
The job comes with a fiduciary duty to act in the best interest of the estate’s beneficiaries.
“There’s a legal obligation to manage the assets and pay off the liabilities of the estate in a manner that doesn’t waste the assets. If the estate is going to take a long time to administer, you need to make sure that the investment portfolio is managed correctly, you’re taking reasonable steps to ensure the safety of all of the assets,” said Mark Biderman, senior vice-president of trust and legal at Cidel Private Bank, which provides executor and other services.
An insolvent estate opens up a whole new host of challenges for executors.
“If creditors need to be paid, typically (executors) are the ones holding the bag at the end of the day,” said Biderman.
There can also be complications when the executor lives in a different jurisdiction than the deceased. An executor might have to put up assets as collateral in order to act if they’re out of province. And if the assets are outside Canada, there’s another country’s laws to navigate.
ClearEstate, a tech-based estate planning and settlement company, recently commissioned a poll that suggested Canadians have contradictory feelings about enlisting a loved one as executor.
Nine in 10 respondents said being an executor can be a complicated and time-consuming job that most people aren’t prepared for. But three quarters said they’d accept the assignment if asked. Nearly two-thirds agreed it’s not fair to expect a family member to handle it on their own.
“It’s not a gift. People take it as an honour and take it as a sign of trust, but the reality is it’s a huge burden,” said ClearEstate CEO and co-founder Davide Pisanu.
A lot of the heavy lifting has to be done during limited business hours.
“There’s a massive tax on society through this process because you’re very often taking people in their 50s and 60s who are still working — sometimes even younger, they have young kids — and then they’re stuck with this massive admin burden of unwinding a loved one’s estate, which is brutal,” said Pisanu.
Saying no is an option. So too is backing out years down the line when life circumstances have changed; in that case, a backup executor could step in if one is named in the will or it goes to the courts. Financial firms can be hired to take the lead on all the bureaucracy and paperwork, with the cost drawn from the estate.
The experts agree it’s worthwhile to sit down with your loved one before they pass to go over where their will is, who they bank with, where their passwords can be found and other crucial information.
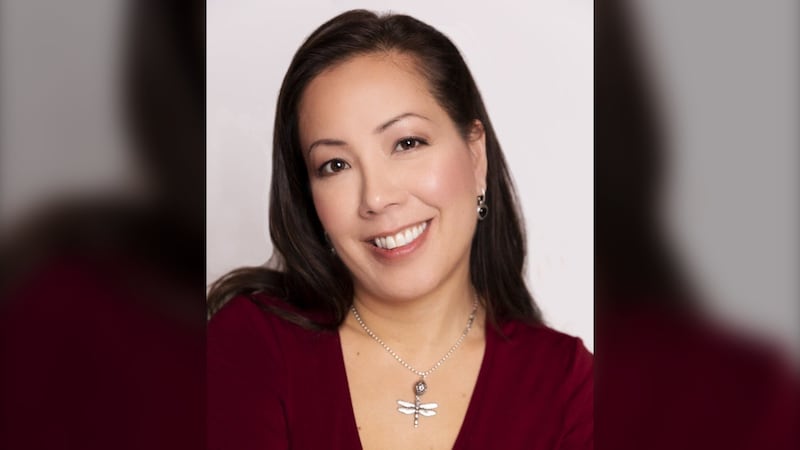
And for those stepping into the role, Chung said record keeping should be immaculate, both because memory can falter in the fog of grief and because of the sheer volume of tasks to keep track of. Keep receipts. Jot down who you’ve spoken to and about what.
But mostly, Chung advises executors to take it one step at a time.
“It’s really stressful, especially if you care very much about the person that you just lost,” she said. “Just try to map out what’s urgent, what isn’t urgent, what absolutely needs me, what things can I potentially outsource, what can I put off for a little bit?”
---
Lauren Krugel, The Canadian Press
This report by The Canadian Press was first published Oct. 22, 2026.